Ghana's Smallholder Finance Push Shows Where African AgTech Is Growing Up
Standfirst: IFC's backing for Absa Bank Ghana and Complete Farmer points to a bigger shift in African agriculture: the next growth wave is not just apps for farmers, but finance, buyers, data and trust built into the same system.
Ghana's agriculture sector has a familiar problem: farmers can produce, buyers need supply, banks want repayment discipline, and yet many smallholders still struggle to access the financing that would let them grow commercially.
A new IFC-backed partnership in Ghana is trying to narrow that gap.
IFC announced partnerships with Absa Bank Ghana and Complete Farmer to expand agricultural finance, support cocoa buying, and help smallholder farmers connect to finance, inputs, agronomy services and buyers. The package includes up to USD 50 million in an unfunded risk participation facility for Absa Bank Ghana to finance Licensed Buying Companies during the cocoa buying season.
Alongside that, IFC, with support from the Business Investment Financing Track of the Global Agriculture and Food Security Program, is providing Complete Farmer with a USD 2.4 million convertible loan. The financing is paired with USD 480,000 in advisory support to strengthen systems and expand farmer financing.
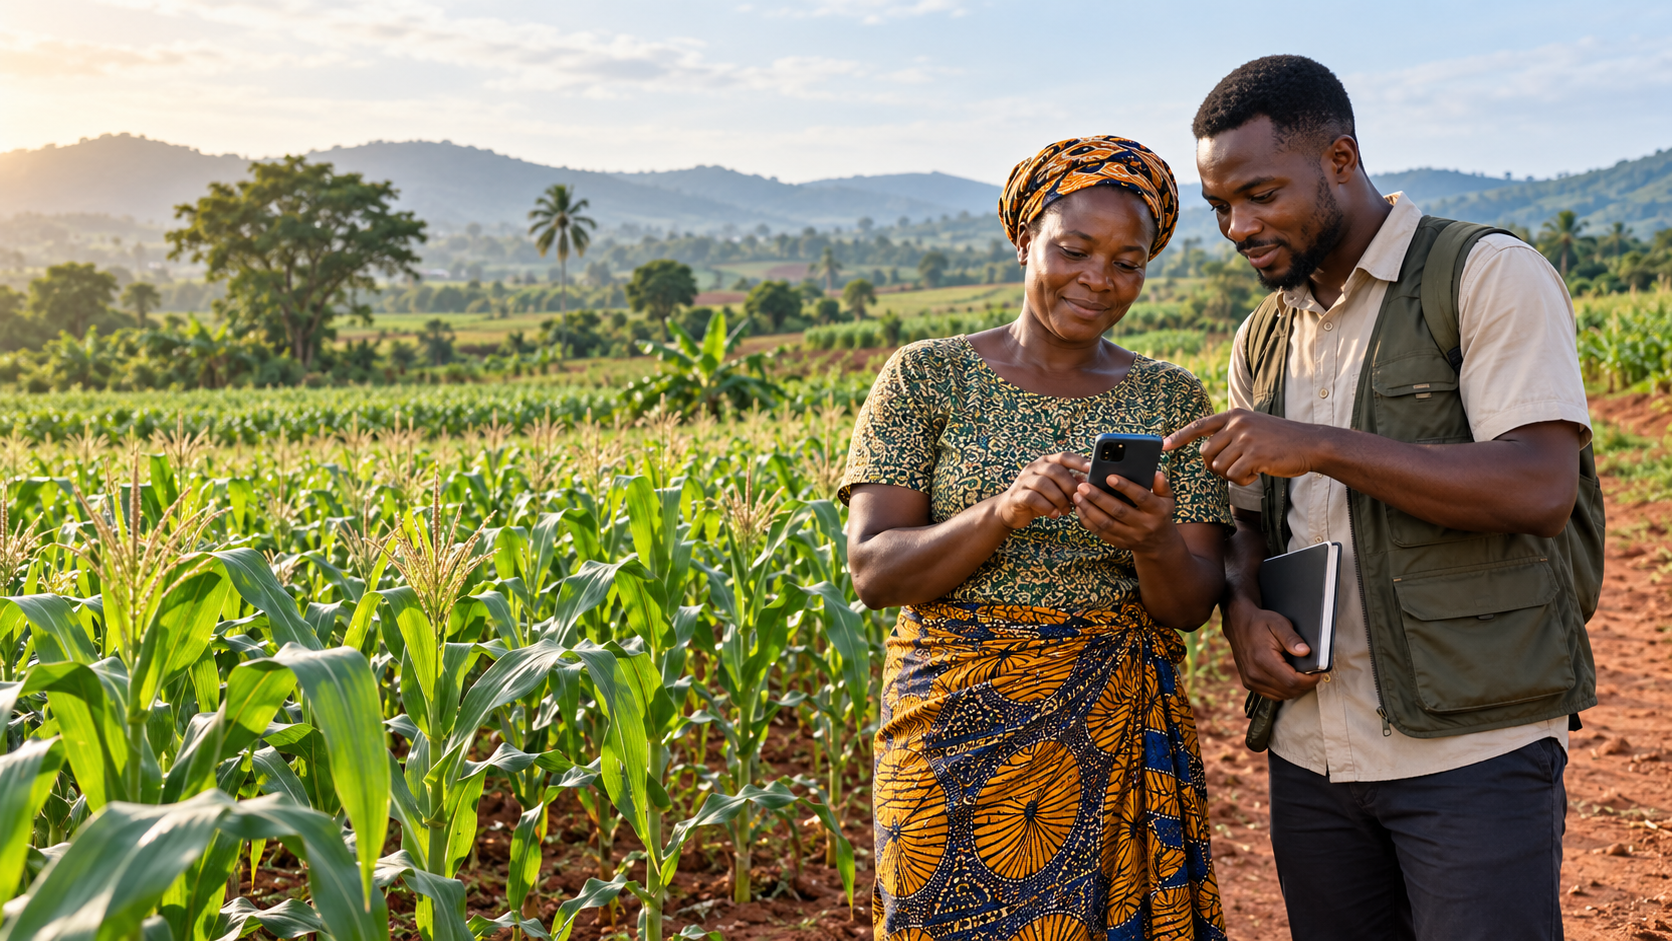
Complete Farmer is a Ghanaian AgTech company whose digital platform connects farmers with buyers, financial institutions, input suppliers and agricultural service providers. IFC says the partnership is expected to support 240,000 farmers by 2030, including by helping farmers access finance.
This is not the loudest African tech story of the week. But it may be one of the more important ones.
The Real Story Is Trust
African agriculture does not lack ambition. It lacks coordination.
Smallholder farmers often need inputs before harvest, technical support during production, reliable buyers after harvest, and payment systems that make lenders comfortable. Banks, meanwhile, need enough data and structure to assess risk. Buyers need predictable quality and volume. Farmers need fairer access to capital without being trapped by opaque middlemen.
The reason this Ghana partnership matters is that it treats finance as part of a larger operating system.
Complete Farmer is not just presenting itself as a farmer-facing app. Its platform is positioned as infrastructure connecting multiple actors: farmers, financiers, suppliers, service providers and buyers. That is where African AgTech is maturing. The winners will not be the companies with the prettiest dashboard. They will be the ones that reduce risk across the value chain.
Why Cocoa Matters
The Absa Bank Ghana portion of the partnership is tied to cocoa buying, one of Ghana's most important export sectors. IFC says the financing facility is expected to support Licensed Buying Companies during the cocoa buying season and help sustain market access for more than 139,000 smallholder farmers.
That matters because cocoa is not just a commodity story. It is a household income story, a foreign-exchange story, a jobs story and a rural resilience story.
When buying companies have access to working capital, farmers are more likely to have reliable market channels. When farmers can connect to buyers and services through better systems, the sector has a better chance of moving from survival economics toward productivity.
The bigger test is whether these tools reach the farmers who have historically been least served by formal finance.
Why This Matters Beyond Ghana
Across Africa, the old agricultural finance model has struggled because risk is scattered everywhere.
Farmers are seen as risky borrowers. Weather is risky. Price swings are risky. Informal records are risky. Fragmented supply chains are risky. Banks often respond by staying conservative, while farmers remain undercapitalized.
Digital platforms can help, but only when they are connected to real commercial demand and real financing partners. A standalone app cannot solve a broken market. A coordinated system can begin to.
That is why this Ghana deal deserves attention from investors, policymakers and diaspora builders. It shows the kind of blended structure African food systems may need: bank capital, development finance, private-sector platforms, advisory support and clear buyer linkages.
For the diaspora, the opportunity is also practical. Many Africans abroad want to invest in agriculture, but informal farm projects can be hard to monitor and easy to mismanage. Stronger platforms and financing rails could eventually create more transparent ways to support farmers, aggregate supply, and participate in food value chains without relying only on personal networks.
The Growth Question
The headline number is useful, but the real measure will be execution.
Can Complete Farmer scale farmer financing without weakening repayment discipline? Can Absa-backed cocoa finance improve liquidity at the right moment in the buying season? Can advisory support help build systems that banks trust? Can farmers capture more value, not just produce more volume?
Those are the questions that will determine whether this is a pilot-style announcement or a scalable model.
Africa does not need AgTech hype. It needs agricultural systems that make farmers more bankable, buyers more reliable, and food value chains more productive.
Ghana's latest smallholder finance push is a signal that the sector is moving in that direction.
Sources
- IFC press release: https://www.ifc.org/en/pressroom/2026/ifc-partners-with-absa-bank-ghana-and-complete-farmer-to-expand-agricultural-finan
- IFC advisory disclosure on Complete Farmer: https://disclosures.ifc.org/project-detail/AS/610763/aap-advisory-complete-farmer
Discover more from ADUNAGOW Magazine
Subscribe to get the latest posts sent to your email.